
Arm Holdings (ARM) develops CPU architectures, system intellectual property and compute platforms used across smartphones, cloud servers, vehicles and connected devices. Its license-and-royalty model provides broad AI semiconductor exposure without owning fabrication plants, while compute subsystems and production silicon are becoming more important. That expansion increases Arm's AI opportunity, yet also raises execution, supply and margin-mix risk.
Its latest quarter showed strong demand across both sides of the model. ARM Fiscal Q1 2027 revenue reached $1.289 billion, up 22% year over year, as royalty revenue rose 22% to $715 million and license revenue grew 23% to $574 million. Data-center royalties more than doubled, making infrastructure adoption the clearest support for the premium valuation.
The ARM stock forecast for 2026 now centers on two competing views:
- The AI royalty and value-per-system case: higher royalty rates, Neoverse adoption and Arm AGI CPU demand could expand Arm's participation in AI infrastructure.
- The execution and valuation case: uneven licensing, production-silicon costs and a premium multiple could overwhelm strong demand if revenue conversion or margins disappoint.
This guide breaks down the ARM stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Arm's July 29 fiscal Q1 2027 release, investor materials and market data through September 4, plus how to trade ARM stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Arm Holdings Investors to Know in September 2026
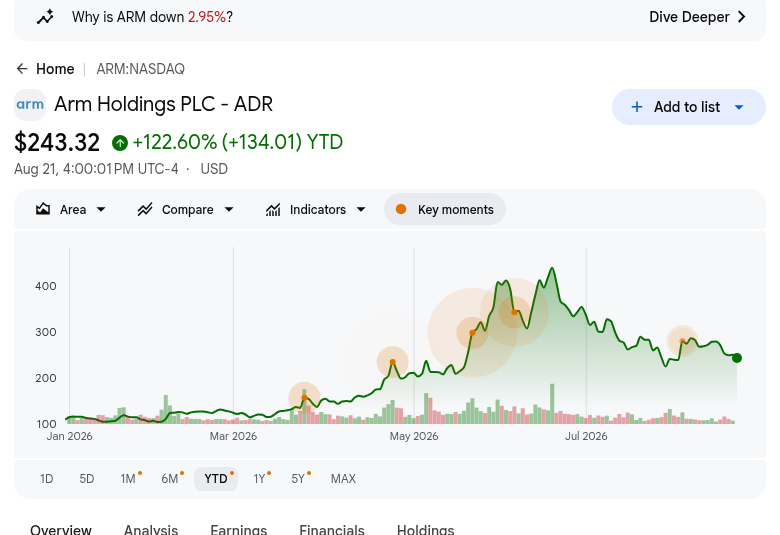
- ARM closed at $252.09 on September 4 after gaining about 115% YTD: The stock had more than doubled in 2026 but still traded well below its $452.70 June peak, showing both strong AI optimism and high sensitivity to changing growth expectations.
- Fiscal Q1 revenue reached $1.289 billion, up 22% year over year: Revenue came about $29 million above the $1.26 billion consensus, while non-GAAP EPS of $0.45 beat the $0.40 estimate. The quarter showed that revenue growth continued translating into earnings despite higher investment.
- Data-center royalties more than doubled as Neoverse shipments passed 1.5 billion cores: The latest 500 million cores shipped in just nine months, compared with six years for the first billion. NVIDIA Vera, Google Axion, AWS Graviton5, Microsoft Cobalt 200, and Qualcomm Dragonfly C1000 show broader Arm CPU adoption across AI infrastructure.
- Arm AGI CPU demand exceeded $2 billion across fiscal 2027 and 2028: Management had previously described a $1 billion opportunity and has already delivered initial products to multiple customers. The larger demand outlook expands Arm’s revenue opportunity, though it still needs to convert into shipments and attractive margins.
- Selected Wall Street targets range from $280 to $500: Bernstein’s $500 Outperform target reflects stronger agentic-AI CPU demand, while Wells Fargo’s $280 Overweight target incorporates more execution and valuation caution. The $220 spread shows broad confidence in Arm’s strategic position but major disagreement over valuation.
What Is Arm Holdings (ARM)?
Arm Holdings is a semiconductor intellectual-property company that designs CPU architectures, processor cores, system IP, development tools and compute subsystems. Customers pay license fees to access the technology and recurring royalties when Arm-based chips ship. Its platforms span smartphones, tablets, PCs, cloud servers, automotive systems, industrial equipment and connected devices. The asset-light model allows revenue to scale across customer shipments without Arm operating its own wafer fabs.
Arm's current strategy moves beyond individual processor cores toward higher-value compute subsystems and Arm-branded production silicon. NVIDIA's Vera CPU, Google's Axion, AWS Graviton5, Microsoft's Cobalt 200 and Qualcomm's planned Dragonfly C1000 all use Arm technology in data centers. Arm has also introduced Performix with Microsoft, MongoDB, Redis and SAP support, strengthening the software layer that helps developers optimize workloads across the AI semiconductor supply chain.
Read More: Top AI Semiconductor Stocks to Buy in 2026: AI Chips and Supply Chain Complete Guide
Arm Holdings (ARM) Q1 FY2027 Earnings Overview: Revenue, EPS and Data-Center Growth
Arm delivered fiscal Q1 revenue of $1.289 billion versus about $1.26 billion expected, non-GAAP EPS of $0.45 versus $0.40 expected, and GAAP net income of $270 million. Royalty revenue rose 22% to $715 million, licensing grew 23% to $574 million, and Q2 revenue guidance reached $1.33 billion to $1.43 billion. The central tradeoff is faster AI growth against rising silicon execution demands.
Read More: Arm Holdings (ARM) Q1 FY2027 Earnings News: Record Revenue and Data-Center Growth Lift Shares 7.40%
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q1 FY2027 revenue |
$1.26B consensus |
$1.289B |
Beat. About $29M above consensus; up 22% YoY. |
|
Q1 non-GAAP diluted EPS |
$0.40 consensus |
$0.45 |
Beat. Five cents above consensus; up 29% YoY. |
|
Q1 GAAP diluted EPS |
— |
$0.25 |
Improved. More than doubled from $0.12 a year earlier. |
|
Q1 GAAP net income |
— |
$270M |
Improved. Increased from $130M a year earlier. |
|
Q1 royalty revenue |
— |
$715M; +22% YoY |
Record. Data-center royalties more than doubled. |
|
Q1 license and other revenue |
— |
$574M; +23% YoY |
Record. High-value renewals supported growth. |
|
Q1 operating cash flow |
— |
$902M |
Strong. Cash generation funded expanding R&D and silicon work. |
|
Q1 non-GAAP free cash flow |
— |
$665M |
Positive. Cash conversion remained strong despite investment. |
|
Q2 FY2027 revenue outlook |
About $1.36B Street view |
$1.33B to $1.43B |
Above midpoint. The $1.38B midpoint exceeded the cited Street view. |
|
Q2 FY2027 non-GAAP EPS outlook |
— |
$0.43 to $0.51 |
Constructive. The midpoint indicates continued earnings growth. |
- Revenue of $1.289 billion grew 22% and beat consensus by about $29 million: Both licensing and royalties contributed, reducing dependence on one revenue stream in the quarter. The result supports Arm's claim that AI demand is broadening across cloud, edge and physical systems rather than remaining limited to a single product category.
- Non-GAAP EPS of $0.45 beat the $0.40 estimate by five cents: GAAP diluted EPS also rose to $0.25 from $0.12 and net income increased to $270 million from $130 million. The earnings expansion shows operating progress, although investors still need to separate underlying economics from stock-based compensation and adjusted measures.
- Royalty revenue increased 22% to a record $715 million: Data-center royalties more than doubled and Armv9 plus compute subsystems raised royalty rates in consumer devices. Growth across both infrastructure and newer architectures matters because sustainable royalty expansion provides recurring economics that can offset volatile timing in large license agreements.
- Operating cash flow reached $902 million and non-GAAP free cash flow reached $665 million: These figures exceeded GAAP operating income and provide resources for engineering, capacity and production-silicon investment. Continued cash conversion would help Arm fund AGI CPU growth without allowing the more capital-intensive business model to erode its financial flexibility.
- Q2 revenue guidance reached $1.33 billion to $1.43 billion: The $1.38 billion midpoint sits above the cited $1.36 billion Street view, and non-GAAP EPS guidance is $0.43 to $0.51. Delivering near the upper ends would reinforce momentum, while a miss would intensify concern about license timing and AGI CPU conversion.
Arm Holdings (ARM) 2026 Investment Outlook: $350 Bull Case vs. $180 Bear Case
The 2026 outlook depends on whether data-center royalties and Arm AGI CPU revenue can expand without weakening the high-margin economics that made Arm's licensing model valuable.
The Bull Case: Data-Center Royalties and AGI CPU Demand Push ARM Toward $350
The Bull Case assumes data-center royalties continue growing well above company-wide revenue as NVIDIA Vera, Google Axion, AWS Graviton5 and Microsoft Cobalt deployments scale. More than $2 billion of indicated AGI CPU demand converts into shipments, while royalty revenue preserves cash generation and offsets the additional manufacturing and working-capital needs of production silicon.
A move toward $350 would require quarterly revenue near or above the $1.43 billion guidance ceiling, continued double-digit royalty growth and evidence that AGI CPU revenue carries disciplined margins. Guidance upgrades, additional high-value licenses and cash flow rising alongside silicon shipments would provide the clearest confirmation; delayed customer conversion would weaken the case.
The Base Case: Royalty Growth Keeps ARM Between $250 and $310
The Base Case assumes royalties and licensing remain Arm's primary earnings engine while compute subsystems and AGI CPU revenue scale gradually. Data-center royalties continue expanding, Armv9 supports value per device and quarterly license timing stays uneven. Operating investment rises, although $665 million of recent non-GAAP free cash flow provides room to fund the roadmap.
Under this scenario, ARM could trade mainly between $250 and $310 as investors balance 22% revenue growth against execution risk and a premium multiple. Revenue within the $1.33 billion to $1.43 billion Q2 range, stable margins and incremental AGI CPU shipments would support the range; slower royalties or weaker cash conversion would challenge it.
The Bear Case: Silicon Delays and Multiple Compression Pull ARM Toward $180
The Bear Case assumes large AGI CPU opportunities move further into future periods as customers change deployment schedules or capacity plans. Licensing remains lumpy, smartphone demand softens and production-silicon costs rise before material revenue appears. Slower royalty growth would then leave operating expenses and supply commitments weighing more heavily on earnings and cash conversion.
A move toward $180 would become more likely if revenue falls below the $1.33 billion guidance floor, data-center royalty growth slows materially or gross-margin commentary weakens as silicon shipments begin. Arm could retain a strong architectural position, yet lower estimates and a compressed growth multiple would dominate the near-term stock outcome.
ARM Stock Price Forecasts for 2026 By Wall Street Analysts
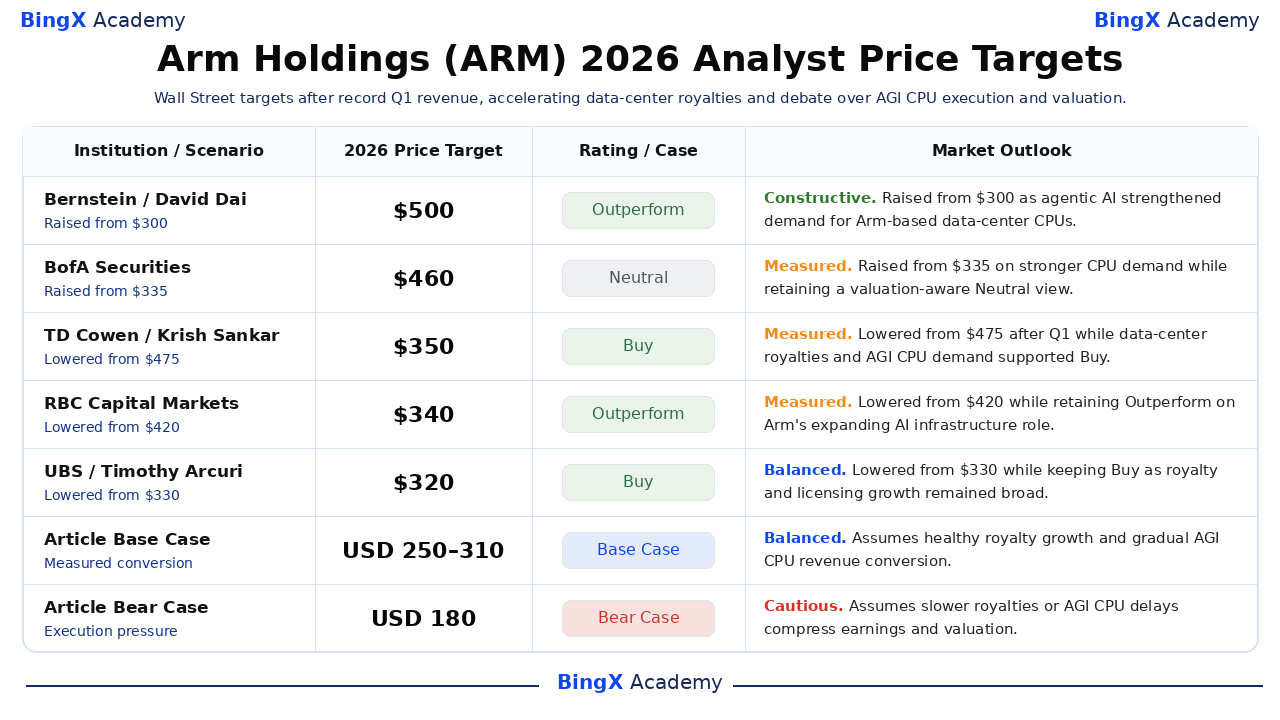
The selected analyst targets span $280 to $500, compared with ARM's $252.09 September 4 close. Bernstein and BofA raised their targets during the June CPU re-rating, while several firms reduced targets after fiscal Q1 despite maintaining positive ratings. The dispersion measures disagreement over valuation and conversion timing; the article scenarios remain separate editorial estimates.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Bernstein |
$500 |
Outperform |
Constructive. June 17: raised from $300 as agentic AI strengthened demand for Arm-based data-center CPUs. |
|
BofA Securities |
$460 |
Neutral |
Measured. June 23: raised from $335 on stronger CPU demand while retaining a valuation-aware Neutral view. |
|
TD Cowen |
$350 |
Buy |
Measured. July 30: lowered from $475 after Q1 while data-center royalties and AGI CPU demand supported Buy. |
|
RBC Capital Markets |
$340 |
Outperform |
Measured. July 30: lowered from $420 while retaining Outperform on Arm's expanding AI infrastructure role. |
|
UBS |
$320 |
Buy |
Balanced. July 30: lowered from $330 while keeping Buy as royalty and licensing growth remained broad. |
|
Wells Fargo |
$280 |
Overweight |
Balanced. July 30: lowered from $320 as execution and valuation risk offset data-center momentum. |
|
Article Base Case |
$250 to $310 |
Base Case |
Balanced. Assumes healthy royalties and gradual AGI CPU revenue conversion. |
|
Article Bear Case |
$180 |
Bear Case |
Cautious. Assumes slower royalties or AGI CPU delays compress earnings and valuation. |
How to Trade Arm Holdings (ARM) Stock on BingX
Trade Arm's data-center royalty, AGI CPU conversion and valuation outlook using BingX TradFi and BingX AI tools. Because ARM can react sharply to licensing timing, earnings and product milestones, traders should define both the catalyst and risk limits before entering a position.
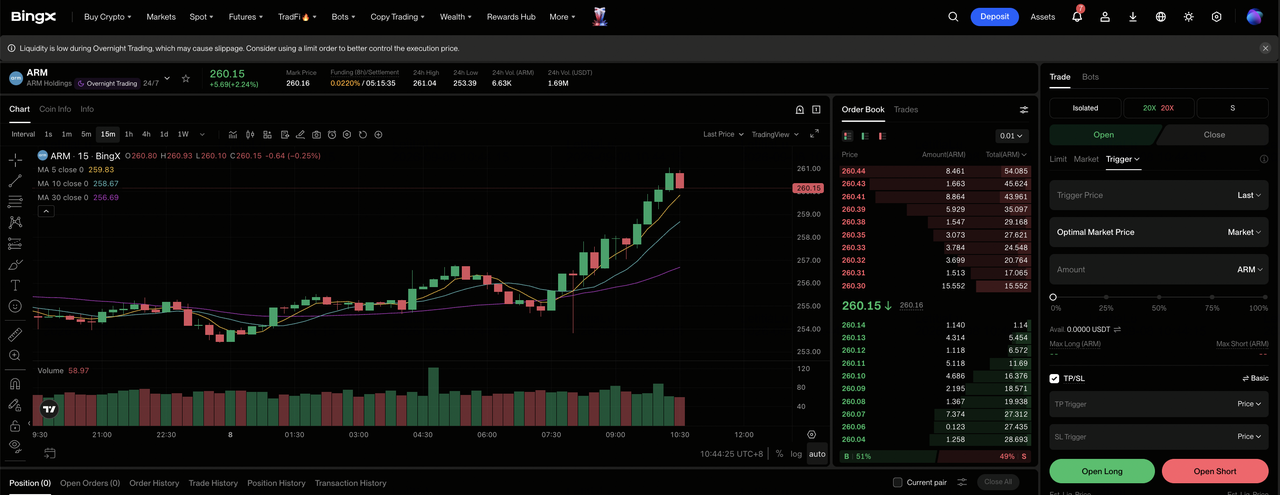
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Arm Holdings (ARM). Search for and select the ARM-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if data-center royalties accelerate and AGI CPU demand converts profitably. Select Open Short if license timing weakens or silicon costs pressure margins.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. ARM's wide $100.02 to $452.70 annual range shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. ARM can react quickly to license wins, royalty trends, earnings guidance, export controls and AGI CPU milestones.
Top 5 Risks to Watch for Arm Holdings Investors in 2026
ARM combines strong AI growth potential with a premium valuation, so execution issues can quickly affect both earnings expectations and the multiple investors are willing to pay.
- Premium valuation leaves little room for disappointment: ARM closed at $252.09 after gaining about 115% YTD, within a 2026 range of $100.02 to $452.70. A modest revenue or EPS miss could therefore trigger multiple compression even if the company remains profitable and growing.
- License revenue can make quarterly growth uneven: Fiscal Q1 license revenue reached $574 million and included large strategic agreements whose timing can vary. Delayed renewals or fewer major deals could weaken near-term revenue before recurring royalties offset the gap.
- Moving into production silicon adds new cost and execution risk: More than $2 billion of AGI CPU demand expands Arm’s opportunity, but manufacturing capacity, inventory, and working capital introduce risks that do not exist in a pure IP-licensing model. Costs arriving ahead of shipments could pressure margins and free cash flow.
- Smartphone and hyperscaler cycles still matter: Higher Armv9 royalty rates can be offset by weaker device shipments, while data-center growth depends partly on a small group of large cloud customers. Slower handset demand or delayed cloud deployments would pressure royalty growth.
- Geopolitics and shareholder concentration can raise uncertainty: Export controls may restrict technology access in important markets, while SoftBank remains Arm’s controlling shareholder. Regulatory changes or governance decisions could narrow the addressable market and raise the risk premium applied to ARM.
Final Thoughts: Should You Invest in ARM Stock in 2026?
Arm enters September with 22% revenue growth, record royalty and licensing revenue, data-center royalties that more than doubled and over $2 billion of indicated AGI CPU demand. Those facts support the AI compute thesis, yet the $252.09 reference price already embeds substantial progress. The key question is whether new silicon revenue can scale without weakening margins or cash conversion.
The $250 to $310 Base Case requires healthy royalties, revenue within guidance and measured AGI CPU commercialization. The $350 Bull Case needs faster data-center adoption and profitable customer conversion, while the $180 Bear Case reflects delays and multiple compression. Conservative investors should monitor data-center royalties, license timing, AGI CPU shipments, gross margin and free cash flow together.
Risk Reminder: ARM scenarios are conditional research estimates, not investment advice or guaranteed returns. Shares and TradFi perpetual contracts can lose value, and leveraged contracts can be liquidated. Review current data, assumptions and BingX terms independently before taking risk.
Related Reading
- Top AI Semiconductor Stocks to Buy in 2026: AI Chips and Supply Chain Complete Guide
- Top AI Compute and GPU Stocks to Buy in 2026: The Shift to Inference and Custom Silicon
- Top AI Data Center Stocks to Buy in 2026: Cloud, Servers, and AI Compute Infrastructure
- Nvidia (NVDA) Stock Price Outlook for 2026: Can Blackwell and Vera Rubin Take NVDA Back to $300?
- Qualcomm (QCOM) Stock Forecast 2026: Can AI and Diversification Push QCOM Above $200?
- Alphabet (GOOGL) Price Prediction 2026: Can 82% Cloud Growth and AI Push GOOGL Stock to $430?
